If you are starting a business in the UK, you need to understand when to register with HM Revenue and Customs (HMRC). The deadline depends on whether you operate as a sole trader, limited company, partnership or another business structure.
Sole traders generally need to register for Self Assessment when their gross trading income exceeds £1,000 in a tax year.
Limited companies must register with Companies House before trading and ensure HMRC knows when they become active for Corporation Tax purposes.
However, changes announced in the October 2026 Budget will affect thousands of small business owners.
From 6 April 2027, the government plans to increase the trading allowance and Self Assessment reporting threshold from £1,000 to £3,000.
Our analysis of the current HMRC rules shows that many business owners also need to consider VAT registration, payroll responsibilities and Making Tax Digital requirements.
Understanding these obligations early can help you avoid penalties, manage your finances and establish your business correctly.
When Do You Need to Register Your Business With HMRC?
The registration deadline depends on the structure of your business and the taxes that apply.
A sole trader can usually start trading immediately without registering. However, a limited company must be legally incorporated before operating as that company.
The following table explains the main requirements.
| Business Type | Registration Requirement | Deadline |
| Sole trader | Register for Self Assessment when gross trading income exceeds £1,000 in 2026/27, or if another registration requirement applies | Usually 5 October after the relevant tax year |
| Limited company | Incorporate with Companies House | Before operating as a limited company |
| Active limited company | Ensure HMRC is notified for Corporation Tax | Within 3 months of becoming active |
| Ordinary partnership | Register the partnership and individual partners | Generally 5 October in the second tax year |
| Limited Liability Partnership | Register with Companies House and meet HMRC tax requirements | Incorporate before operating as an LLP |
| VAT-liable business | Register for VAT | According to the applicable VAT threshold test |
| Business employing staff | Register for PAYE where required | Before the first payday |
These deadlines are separate. Registering a limited company does not automatically satisfy every VAT, payroll or personal tax obligation.
For business owners who are unsure which structure to choose, the government’s business setup guidance explains the main legal and tax differences.
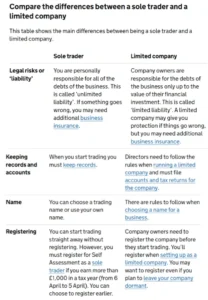
HMRC business setup guidance comparing sole traders and limited companies.
Do Sole Traders Need to Register With HMRC?
Yes, most sole traders must register for Self Assessment once their gross trading income exceeds £1,000 during the tax year, under the rules applying in 2026/27.
A sole trader is someone who owns and operates a business personally. This includes freelancers, consultants, tradespeople, delivery drivers and individuals selling products for profit.
Unlike limited companies, sole traders do not need to incorporate with Companies House.
For example, suppose you start a freelance graphic design business in September 2026. By January 2027, you have received £2,400 from clients.
Because your gross trading income exceeds £1,000 during the 2026/27 tax year, you would normally need to register for Self Assessment by 5 October 2027.
Importantly, HMRC considers your trading income before deducting business expenses.
If you earn £1,500 from customers but spend £900 on supplies, your gross trading income is still £1,500, even though your profit is only £600.
You may still have no Income Tax to pay after applying the relevant allowances and reliefs. However, the registration requirement and the amount of tax payable are two different matters.
If you want further clarification about small trading income, see our analysis of whether you need to register a business when earning less than £1,000.
Can You Register Before Earning £1,000?
Yes. HMRC allows eligible individuals to register earlier.
You may need to register even when your income is below the threshold if you:
- Want to claim tax relief for qualifying business losses.
- Need to prove self-employment for Tax-Free Childcare or certain benefits.
- Want to make voluntary Class 2 National Insurance contributions.
- Need to register as a subcontractor under the Construction Industry Scheme.
- Have another reason to complete a Self Assessment tax return.
You should not automatically assume that earning less than £1,000 means registration is unnecessary in every situation.
The official register as a sole trader service explains the circumstances in which HMRC requires registration.
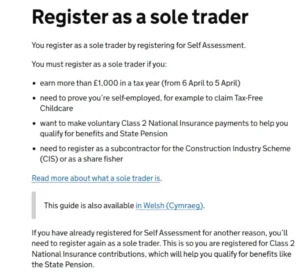
Official HMRC registration requirements for sole traders earning more than £1,000.
Is the HMRC Registration Threshold Increasing to £3,000 in 2027?
Yes. The government announced in its 28 October 2026 Budget that it intends to increase the trading allowance and corresponding Self Assessment reporting threshold to £3,000 from 6 April 2027.
The change is expected to apply from the 2027/28 tax year, subject to legislation in the Finance Bill 2026–27.
This is an important development for freelancers, small-scale online sellers and people earning occasional income from additional work.
| Tax Year | Trading Allowance and Reporting Threshold | Position |
| 2025/26 | £1,000 | Existing rules |
| 2026/27 | £1,000 | Existing rules |
| 2027/28 | £3,000 | Announced change, subject to legislation |
For example, someone earning £2,000 from qualifying freelance work during 2026/27 would generally need to register for Self Assessment.
However, someone earning the same amount during 2027/28 may no longer need to register solely because of that qualifying trading income, once the new rules take effect.
The difference matters because business owners should apply the rules for the tax year in which the income arises, rather than assuming that a newly announced threshold applies retrospectively.
The trading allowance is also not available for every type of income. Earnings from certain connected companies, partnerships and employers are excluded, while partnerships themselves are subject to separate rules.
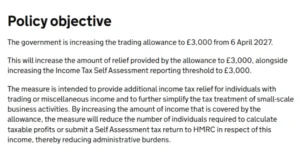
October 2026 Budget announcement confirming the planned increase in the trading allowance to £3,000.
What Is the Deadline for Registering as Self-Employed?
The standard Self Assessment registration deadline is 5 October following the end of the tax year in which you became required to register.
UK tax years run from 6 April to 5 April.
For example:
| Trading Period | Registration Deadline | Online Tax Return Deadline |
| 6 April 2025 – 5 April 2026 | 5 October 2026 | 31 January 2027 |
| 6 April 2026 – 5 April 2027 | 5 October 2027 | 31 January 2028 |
| 6 April 2027 – 5 April 2028 | 5 October 2028, if registration is required | 31 January 2029 |
As of 30 October 2026, the registration deadline for new Self Assessment taxpayers reporting income from 2025/26 has already passed.
Anyone who should have registered but missed 5 October 2026 should take action as soon as possible rather than waiting until the tax return deadline.
HMRC introduced an improved online Self Assessment registration service in September 2026.
Myrtle Lloyd, HMRC’s Chief Customer Officer, explained:
“Anyone new to Self Assessment may not realise they need to register before they can submit their tax return.”
Her statement highlights a distinction that is easy to overlook: registering for Self Assessment and submitting your annual tax return are separate processes.
Once registered, you receive a Unique Taxpayer Reference, known as a UTR, which HMRC uses to identify your tax records.
Can You Start Trading Before Registering With HMRC?
Yes, if you are operating as a sole trader, you can normally begin trading before registering with HMRC.
You do not need to wait until you have a UTR before accepting your first customer or issuing an invoice.
However, you must keep appropriate business records from the beginning.
This includes recording customer payments, business expenses, invoices and other financial transactions.
For example, suppose you start selling handmade candles in November 2026. During the first few months, you earn £450.
You can continue operating without immediate Self Assessment registration if no other registration requirement applies.
If your gross trading income subsequently exceeds £1,000 before 5 April 2027, you would normally need to register by the October 2027 deadline.
A limited company is different. You must incorporate it with Companies House before trading in the company’s name because the company does not legally exist until incorporation.
You may trade personally before incorporation, but that activity has different legal and tax consequences.
When Must a Limited Company Register With HMRC?
A limited company must be registered with Companies House before it begins operating as a company.
Once incorporated, it becomes a separate legal entity from its directors and shareholders.
When you register a company through the standard GOV.UK online incorporation service, it will usually be set up for Corporation Tax at the same time.
However, you must still ensure HMRC knows when your company becomes active.
Generally, HMRC must be notified within three months of the company becoming active for Corporation Tax purposes.
Business activity may include providing services, buying and selling goods, earning trading income or other activities that bring the company within the Corporation Tax rules.
What If Your Limited Company Is Dormant?
A dormant company has been incorporated but is not carrying on relevant business activity.
For example, you may register a company in December 2026 to reserve your preferred business name but delay commercial operations until July 2027.
In this situation, you should understand the distinction between incorporation, dormancy and becoming active for Corporation Tax.
A dormant company may not have to submit a Corporation Tax return for a period HMRC accepts as dormant. However, Companies House filing obligations can still apply.
Once the company becomes active, the relevant HMRC notification requirements begin.
For business owners reviewing future tax liabilities, our article on how much Corporation Tax a limited company pays explains how profits are taxed and why registration is only the first stage of company tax compliance.
How Much Does It Cost to Register a Limited Company?
As of October 2026, the standard Companies House incorporation fee is £100 for an online application and £124 for a paper application.
HMRC registration for Corporation Tax itself does not normally carry a separate registration fee.
Additional costs may arise if you use a company formation agent, accountant, registered office service or commercial software.
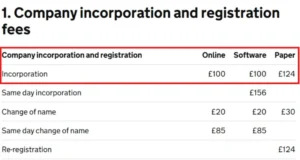
Current Companies House incorporation fees for online and paper applications.
Do Partnerships and LLPs Need to Register With HMRC?
Yes. Partnerships have registration obligations that differ from those of individual sole traders.
An ordinary business partnership generally involves two or more people sharing responsibility for operating a business.
The partnership must register for Self Assessment, and each partner must register separately where required.
One person becomes the nominated partner, responsible for submitting the partnership tax return.
The registration deadline is generally 5 October in the partnership’s second tax year.
A Limited Liability Partnership, or LLP, must also be incorporated with Companies House and meet its relevant HMRC tax obligations.
Most ordinary trading LLPs are taxed broadly as partnerships, with members reporting their respective profit shares individually rather than the LLP automatically paying Corporation Tax.
However, special tax treatments may apply in particular circumstances.
When establishing a partnership, it is also sensible to agree how profits, business expenses and responsibilities will be shared.
An informal agreement may appear sufficient at the beginning, but clear financial records and a written partnership agreement can help avoid disagreements as the business expands.
Do You Need to Register an Online Business or Side Hustle?
Running a business online does not automatically exempt you from UK tax registration requirements.
Whether you earn money through an online marketplace, social media platform, freelance website or independent ecommerce store, HMRC generally applies the normal trading income rules.
Examples include selling handmade products, providing freelance writing services, earning creator income and running paid online training.
However, there is an important distinction between genuine trading activity and occasionally selling personal belongings.
Selling an unwanted second-hand item does not normally mean that you are operating a business.
Repeatedly buying products with the intention of reselling them for profit is more likely to be treated as trading.
HMRC has also clarified that the £1,000 threshold is generally assessed against combined qualifying trading income rather than separately for every side hustle.
For example:
| Income Source | Annual Gross Trading Income |
| Freelance writing | £650 |
| Online tutoring | £500 |
| Total | £1,150 |
Under the 2026/27 rules, the combined £1,150 exceeds the £1,000 threshold.
Being employed elsewhere does not remove your responsibility to report self-employed income when required.
It is also worth remembering that digital platforms may report seller information to tax authorities under applicable reporting rules. Platform reporting is not, by itself, proof that a seller owes tax.
When Do You Need to Register for VAT?
VAT registration follows a different set of rules from Self Assessment.
As of October 2026, most UK-established businesses must register for VAT when their total VAT-taxable turnover exceeds £90,000 over any rolling 12-month period.
Registration may also be required if you expect taxable turnover to exceed £90,000 in the next 30 days alone.
The distinction between a rolling 12-month period and a tax year is important.
Businesses should check their VAT-taxable turnover at the end of every month rather than waiting until April.
How Quickly Must You Register After Reaching the VAT Threshold?
If you exceed the threshold based on the previous 12 months, you normally have 30 days from the end of the month in which you crossed it to register.
For example, suppose your rolling 12-month VAT-taxable turnover first exceeds £90,000 in October.
You would normally need to register by 30 November, with an effective VAT registration date of 1 December.
Different timing applies if you expect to exceed £90,000 in the next 30 days alone. In that case, you must register by the end of that 30-day period, and your effective registration date is generally the date you first expected to exceed the threshold.
Businesses based outside the UK that make relevant taxable supplies in the UK can also face different registration rules, including circumstances where there is no turnover threshold.
Should You Register for VAT Voluntarily?
Some businesses register for VAT before reaching the compulsory threshold.
This can be useful where they make significant VAT-bearing purchases and sell mainly to VAT-registered business customers.
However, voluntary registration creates additional responsibilities, including accurate VAT accounting, digital records and periodic returns.
For a business selling mainly to individual consumers, the effect of VAT on pricing and profit margins should be assessed carefully.
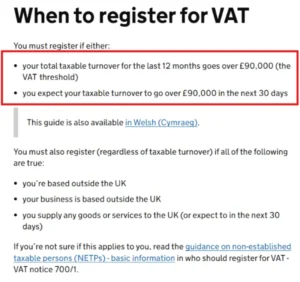
HMRC’s £90,000 VAT registration threshold and the rules for checking turnover.
When Must a Business Register for PAYE?
Businesses generally need to register with HMRC as an employer when they start employing staff and must operate PAYE.
PAYE is the system used to report employee earnings and collect Income Tax and National Insurance where applicable.
Employers must register before the first payday, and HMRC normally does not allow registration more than two months before employees begin receiving pay.
Some limited companies must also register for PAYE when paying their directors through payroll.
Registration is not necessarily required for every arrangement involving a very small payment or casual work, so businesses should check the PAYE reporting conditions for their circumstances.
Before taking on an employee, consider the wider responsibilities involved, including employment contracts, workplace pension obligations, right-to-work checks and employers’ liability insurance where required.
Will Making Tax Digital Affect Your HMRC Registration?
Making Tax Digital for Income Tax is another significant change affecting self-employed people and landlords.
The system requires eligible taxpayers to maintain digital records, send quarterly income and expense updates using compatible software, and complete their annual tax reporting.
Its implementation is being introduced in stages.
| Start Date | Qualifying Income Threshold |
| 6 April 2026 | More than £50,000 |
| 6 April 2027 | More than £30,000 |
| 6 April 2028 | More than £20,000 |
These thresholds concern qualifying gross income from self-employment and property. They are separate from the £1,000 trading allowance and the proposed £3,000 allowance for 2027/28.
Craig Ogilvie, HMRC’s Director of Making Tax Digital, said in October 2026:
“Signing up now means you can prepare and familiarise yourself with the process before it becomes mandatory next April.”
His advice is particularly relevant to established sole traders whose qualifying income brings them into the April 2027 phase.
Rather than treating digital reporting as a last-minute administrative task, affected businesses should consider their software, record-keeping arrangements and existing tax records in advance.
Our assessment is that compatible accounting software can be especially useful once a business has multiple income sources, employees or VAT obligations.
For practical options, see our comparison of accounting software for small businesses in the UK, including tools for bookkeeping and digital tax reporting.
How Do You Register Your Business With HMRC?
The registration process depends on your business structure.
How Do Sole Traders Register?
To register as a sole trader, you generally need to complete the following steps:
- Confirm that your business activity qualifies as self-employment.
- Check whether you need to register for Self Assessment.
- Visit the official GOV.UK sole trader registration service.
- Sign in or create the required government online account.
- Provide your personal and business information, including your National Insurance number.
- Complete the registration process and retain your confirmation.
- Obtain your UTR and prepare your financial records for reporting.
If you are already registered for Self Assessment for another reason, HMRC may still require you to register your self-employment details.
You should not unnecessarily create duplicate tax records.
How Do Limited Companies Register?
Limited companies must first complete incorporation with Companies House.
This involves selecting a company name, providing director and shareholder details, identifying people with significant control, choosing a registered office and confirming the company’s legal arrangements.
After incorporation, check whether the company has been set up for Corporation Tax and ensure HMRC is informed when it becomes active.
You may also need to register for VAT, PAYE or other taxes depending on the nature of your operations.
A UTR issued to the company is different from an individual’s personal Self Assessment UTR.
What Happens If You Register Your Business Late?
Failing to register when required can lead to penalties, interest and additional administrative difficulties.
However, the consequences depend on what obligation was missed.
Missing the Self Assessment registration deadline is not necessarily the same as filing a tax return late.
For example, a standard £100 initial late-filing penalty can apply when a required Self Assessment tax return is submitted after its filing deadline. That charge should not be presented as an automatic fixed penalty simply for missing the 5 October registration date.
Additional penalties may arise for failing to notify HMRC of a tax liability, depending on the circumstances.
Late VAT registration can also produce liabilities from the effective date on which registration should have applied.
Where tax remains unpaid, interest may be charged.
If you have missed a deadline, the sensible next step is to notify HMRC promptly, establish your actual liability and complete any outstanding submissions.
Where the circumstances are complicated, seek advice from a qualified accountant or tax adviser.
What Business Records Should You Keep After Registration?
Proper record-keeping is essential because registration is only the beginning of your business’s tax responsibilities.
Depending on your business structure, you may need records of:
- Sales, invoices and customer payments.
- Business purchases and allowable expenses.
- Bank transactions and supplier invoices.
- Stock, equipment and other relevant assets.
- Employee payments and payroll deductions.
- VAT transactions and digital tax submissions.
- Mileage and business travel expenses.
- Tax returns, HMRC correspondence and payment confirmations.
A separate business bank account is not normally a legal requirement for sole traders, but it can make financial reporting easier.
Limited companies should keep company finances separate from the personal finances of directors and shareholders.
Business records should also be retained for the applicable statutory period, which varies according to the tax and business structure.
What Are the Most Common HMRC Registration Mistakes?
Some mistakes can create unnecessary costs even when the business itself is relatively small.
The most significant errors include confusing turnover with profit, assuming employment income covers side-hustle taxation, and overlooking the difference between HMRC and Companies House.
Other avoidable problems include relying on outdated tax thresholds, failing to register after exceeding the VAT limit, and assuming that a company remains dormant when its activities have changed.
The October 2026 Budget adds another potential source of confusion.
A business owner should not apply the proposed £3,000 trading allowance to the 2026/27 tax year simply because the government has announced that the change will begin in April 2027.
We also recommend paying attention to the difference between registration dates, return-filing dates and tax payment deadlines.
These events may fall months apart, and meeting one obligation does not automatically mean every requirement has been satisfied.
Conclusion
Understanding when you need to register your business with HMRC is essential for operating legally and managing your tax responsibilities in the UK.
For the 2026/27 tax year, sole traders generally need to register for Self Assessment when their gross trading income exceeds £1,000, unless an exception or another registration requirement applies.
Limited companies must be incorporated before operating in the company’s name and must ensure their Corporation Tax obligations are addressed when they become active.
Businesses also need to monitor the separate registration rules for VAT, PAYE and partnerships.
The government’s announcement that the trading allowance and corresponding reporting threshold will rise to £3,000 from April 2027 is particularly important for people starting smaller businesses or earning occasional trading income.
Ultimately, the right approach is to identify your business structure, understand the relevant threshold for the tax year, maintain accurate records and complete registration before the applicable deadline.
Frequently Asked Questions
Do I Need to Register My Business With HMRC If I Earn Less Than £1,000?
Usually not solely because of qualifying trading income in 2026/27, although other circumstances may require registration. The government plans to raise the trading allowance to £3,000 from April 2027, subject to legislation.
Can I Register My Business With HMRC for Free?
Yes. Sole trader Self Assessment registration is free, as are ordinary HMRC tax registration processes. Companies House charges separate fees for incorporating limited companies.
Do I Need to Register With HMRC If I Already Have a Full-Time Job?
You may need to register if you also earn self-employed income above the applicable threshold. Paying tax through PAYE employment does not automatically cover separate business income.
Do I Need a UTR Before Starting My Business?
Sole traders can generally begin trading before receiving a UTR, provided they register by the relevant deadline. Limited companies must first be legally incorporated before trading as that company.
How Long Does HMRC Registration Take?
Processing times vary according to the registration type and personal circumstances. HMRC’s improved online Self Assessment service can streamline registration, but you should allow sufficient time to receive and access the tax references needed for filing.